After an acquisition, the buyer must record the acquired assets as of the acquisition date. For plant and stock, the seller's fixed asset register and stock ledger are the starting point. These records often do not match the floor. An opening balance sheet count finds the differences before they go into your opening balances.
Use this checklist to plan the count. It shows who owns each step, how each step relates to the acquisition date, and which evidence to keep. It applies to fixed assets and industrial stock, such as raw materials, work in process, finished goods and spare parts.
Who owns each step
| Role | What this role owns |
|---|---|
| Buyer controller | Count scope, cutoff rules, sign-off on the reconciliation and the opening balances |
| Integration or deal lead | Site access, the site list, the acquisition date and the legal entity list |
| Seller or site contact | The register and stock ledger extracts, movement records, safety rules and escort on site |
| Count team (internal or third party) | Count plan, tags, blind counts, recounts, reconciliation files and the exception report |
| Valuation team | Fair values, using the verified asset list as input |
| Auditor | Observation of the count and test counts, if the auditor decides to do them |
Write the owner of each step in the count plan. When a step has no owner, it often has no evidence.
The checklist
Before close: get the records and set the rules
- Get the seller's fixed asset register, with asset number, description, location, cost and in-service date.
- Get the stock ledger extract by item, location and quantity.
- Get the site list and the legal entity for each site.
- Record the acquisition date. The count date and the roll-to-date work depend on it.
- Agree the scope: which sites, which asset classes and which stock types.
- Agree the cutoff rules for receipts, issues, shipments, additions, disposals and transfers.
- For a carve-out, agree the split rules. These come from the transaction documents and your instructions.
Plan the count against the acquisition date
- Choose a count date as near to the acquisition date as the sites permit.
- If the count date is not the acquisition date, plan the roll-back or roll-forward now. List the movement records that you will need for the period between the two dates.
- Decide the tag standard for fixed assets that do not have a usable tag (barcode or RFID). See our asset tagging services for tag types.
- Send the count plan and the schedule to your auditor, if the auditor wants to observe.
- Confirm site access, safety rules and a site contact for each site.
Count day: fixed assets and industrial stock
- Count each fixed asset at its location. Record the description, make, model and serial number where visible.
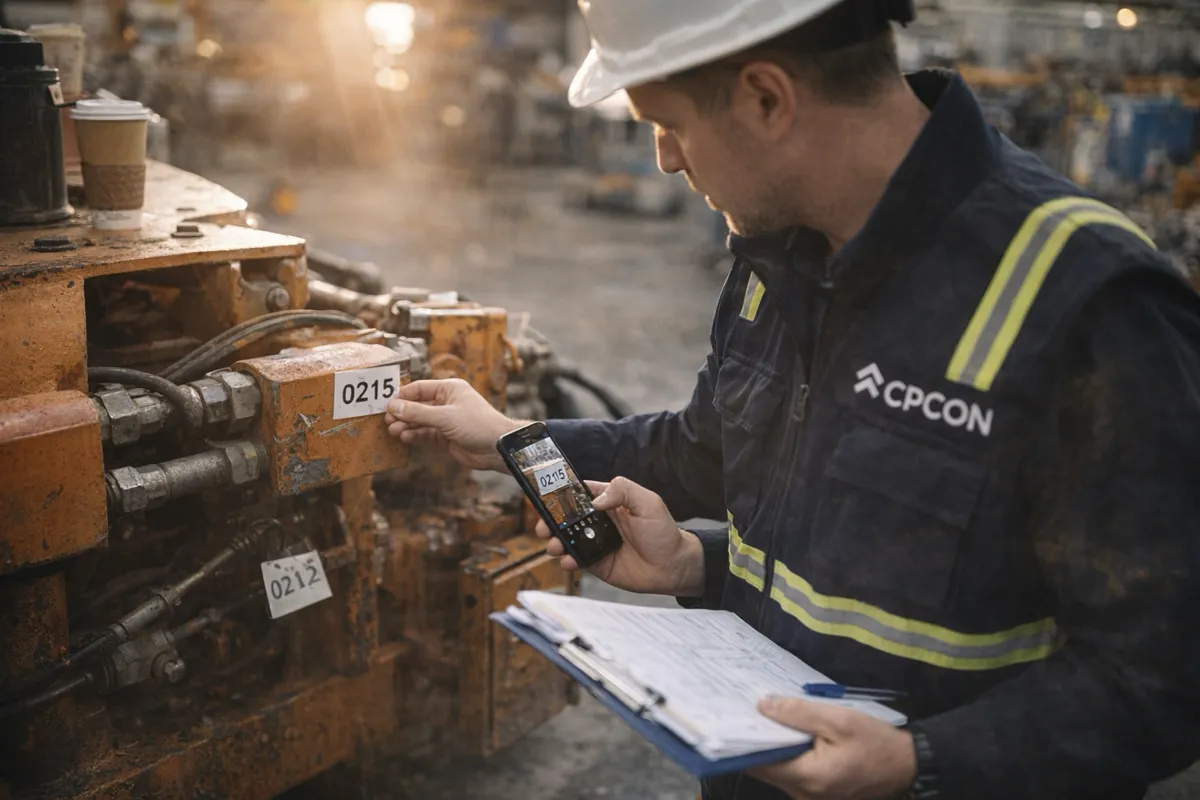
- Apply a durable tag to each fixed asset that does not have a usable tag. Link each tag to one register line.
- Count stock by item and location. Use blind counts, so that the counter does not see the book quantity.
- Recount where the first count and the records do not agree.
- Record the legal entity for each asset and stock location at shared sites.
- Record condition notes where they are in scope.
- Freeze or log all movements during the count, as the cutoff rules say.
Reconcile the count to the register and the stock ledger
- Match each counted fixed asset to a register line. Mark each line as matched, missing or not on the register.
- Search again for each missing asset at the site and in nearby areas before you list it as an exception.
- Match stock counts to the stock ledger by item and location. Record each difference.
- Record wrong descriptions and wrong locations as separate exceptions.
Roll the count to the acquisition date
- For stock, use the receipts, issues and shipments between the count date and the acquisition date.
- For fixed assets, use the additions, disposals and transfers between the two dates.
- Keep the source document for each movement that you use.
- Show the count quantity, each movement and the quantity at the acquisition date on one schedule.
Build the evidence pack
- Count files for each fixed asset and stock item, with location and tag number.
- The reconciliation to the acquired register and to the stock ledger.
- The exception report, line by line, with search notes.
- The roll-to-date schedule and its source documents.
- The method memo: count plan, cutoff rules, recount rules and controls.
- For a carve-out, a register and a stock list for each legal entity.
Hand off and close the exceptions
- Give the verified asset list to the valuation team.
- Give the evidence pack to the auditor for the opening balance sheet audit.
- Get a decision from the controller on each exception. Record the decision and the date.
- Load the clean register into the buyer's system, with the new tag numbers.
Mistakes that weaken the opening balances
- No owner for the cutoff. Stock moves during the count, and nobody records it. The roll-to-date schedule then has gaps.
- Count date set with no roll plan. The team counts on a convenient date but does not keep the movement records for the period between the dates.
- Exceptions with no decision. Missing assets stay on a list, and nobody decides the accounting.
- One file for two entities. At a shared site, the count does not record the entity. The carve-out register then needs a second visit.
- Tags that do not link to the register. New tags go on assets, but the tag numbers do not go into the register.
For a wider fixed asset checklist that is not tied to a deal, see our fixed asset verification checklist.
Need a team to run this checklist? CPCON does opening balance sheet counts for acquired fixed assets and industrial stock. We count, tag, reconcile and roll the count to the acquisition date. Send us the sites and the acquisition date, and we reply with a written quote.
Frequently asked questions
What is an opening balance sheet count checklist?+
It is a list of the steps for a physical count after an acquisition. It shows the records to get, the count plan, the count, the reconciliation, the roll to the acquisition date and the evidence to keep. It also shows who owns each step.
Must the count happen on the acquisition date?+
No. Many teams count on a different date. Then they roll the quantities back or forward to the acquisition date, with the movement records between the two dates. Plan this before the count, so that you keep the correct records.
Who should own the opening balance sheet count?+
The buyer controller usually owns the scope, the cutoff rules and the sign-off. A count team does the field work and the reconciliation. The valuation team and the auditor use the results. Write each owner in the count plan.
What goes in the evidence pack?+
The count files, the reconciliation to the register and the stock ledger, the exception report, the roll-to-date schedule with its source documents, and the method memo. For a carve-out, add a register and a stock list for each legal entity.
Does the count set the fair value of the assets?+
No. The count gives quantities, locations, tag numbers and condition notes. The valuation team sets the fair values. The count gives them a correct list to start from.
Plan your opening balance sheet count.
Tell us the sites, the asset types and the acquisition date. We reply with the scope, the crew plan and a written quote.
Get a count proposalRelated: transaction inventory verification · fixed asset inventory services
30+ years of experience · 2,500+ clients · Projects on every continent
This article gives general information. It is not legal, accounting or audit advice. Your auditor and advisors make the accounting decisions.