Opening Balance Sheet Counts for Acquired Fixed Assets and Stock
You bought the plant. Now you need a correct list of what you bought. We count the acquired fixed assets and industrial stock. Then we reconcile the count to the register and roll it to the acquisition date.
Written quote · Fixed assets and stock in one plan
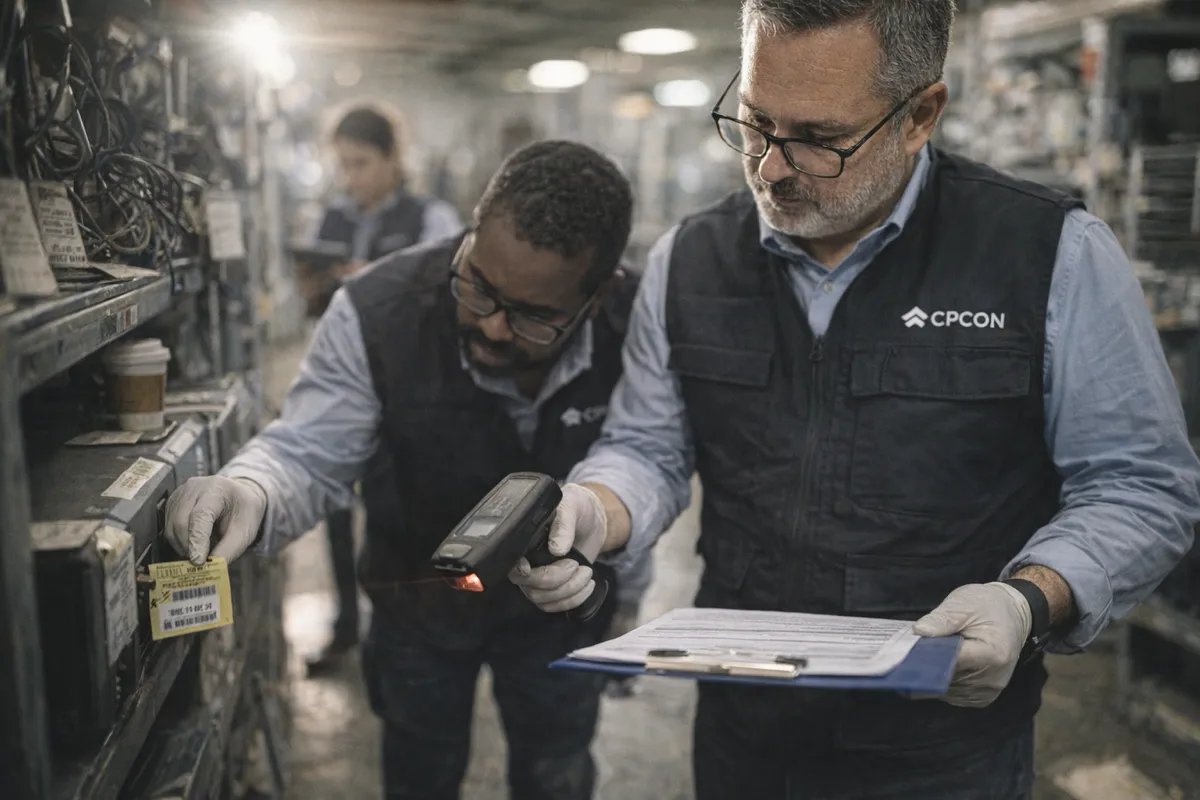
The acquired register does not match the floor
At close, the buyer gets the seller's fixed asset register and stock ledger. These records often do not match the floor. Some assets were scrapped but stay on the register. Some assets are on the floor but not on the register. Stock quantities in the ledger can differ from the bins.
The buyer must record the acquired assets as of the acquisition date. Under ASC 805 acquisition accounting and IFRS 3, the buyer measures these assets at acquisition-date fair values. The fair value work needs a correct list of assets. A wrong list gives wrong opening balances. It also gives wrong depreciation after close.
An opening balance sheet inventory count gives you that list. We count what exists, reconcile it to the records and date it to the acquisition date. For other deal counts, such as closing counts and lender counts, see transaction inventory verification.
What we count: fixed assets and industrial stock
One plan covers both asset types at each site.
- Fixed assets. Machinery, production lines, mobile equipment, IT equipment, furniture and building equipment. This is the same field method as our fixed asset inventory services.
- Industrial stock. Raw materials, work in process, finished goods, spare parts and MRO stock. This is the same field method as our industrial inventory counting services.
- Data on each item. Location, description, make, model and serial number where visible, tag number and condition notes where in scope.
We keep two outputs. The fixed asset count goes to the acquired register. The stock count goes to the stock ledger.
How the count works
1.Plan
We get the acquired register, the stock ledger, the site list and the acquisition date. We agree the count date, the scope and the cutoff rules with you. If your auditor wants to observe, we share the plan before the count.
2.Tag
We apply durable barcode or RFID tags to fixed assets that do not have a usable tag. Each tag links one asset to one register line. For tag types and standards, see our asset tagging services.
3.Count
Our crews count each fixed asset and each stock location. We use blind counts, so the counter does not see the book quantity. We recount where the first count and the records differ.
4.Reconcile
We match each counted asset to the register. Each line shows as matched, missing or not on the register. We match stock counts to the stock ledger by item and location.
5.Roll to the date
The count date and the acquisition date are often different. Then we roll the quantities back or forward to the acquisition date. We use the records of movements between the two dates. For stock, these are receipts, issues and shipments. For fixed assets, these are additions, disposals and transfers.
Carve-outs: split by entity and site
In a carve-out, the buyer takes only part of the seller's business. Sometimes one site holds assets for two legal entities. The carve-out fixed asset register must show only the assets that transfer.
- Split rules first. Before the count, we agree the split rules with you. These rules come from the transaction documents and your instructions.
- Entity on each line. During the count, we record the entity and the site for each asset and stock location.
- Shared assets on a separate list. Assets that both entities use go on a separate list. You decide where they go.
- One file for each entity. You get a register and a stock list for each entity. These support the carve out financial statements.
For related work after the deal, see our post-merger asset consolidation project.
What you receive
- Count files. Each fixed asset and stock item, with location and tag number.
- Reconciliation to the acquired register. Matched, missing and not-on-register lines for fixed assets. Count against ledger for stock.
- Exception report. Missing assets, assets not on the register, wrong descriptions and wrong locations, line by line.
- Roll-to-date schedule. The movements between the count date and the acquisition date, with the source documents we used.
- Carve-out split. A register and stock list for each legal entity, where in scope.
- Method memo. The count plan, the cutoff rules, the recount rules and the controls we used.
Your valuation team can use these files as the verified list for purchase price allocation. Your auditor can use them to review the opening balance sheet audit trail. Your integration team can load the clean register into your system for post acquisition integration.
Questions from controllers and deal teams
What is an opening balance sheet inventory count?+
It is a physical count of the fixed assets and stock that a buyer acquires. The count shows what exists at each site. We then roll the results to the acquisition date. The buyer uses the results to set the opening records of the acquired business.
What do you need from us before the count?+
We need the acquired fixed asset register, the stock ledger extract and a site list. We also need the acquisition date and the names of the legal entities. A site contact and safety rules for each site help us plan the crew.
What happens to assets that are on the register but not on the floor?+
We search for each missing asset at the site and in nearby areas. If we cannot find it, we list it on the exception report. The report shows the register line, the last known location and our search notes. You and your advisors then decide on the accounting.
Can you split one site between two legal entities?+
Yes. Before the count, we agree the split rules with you. These rules come from the transaction documents and from your instructions. During the count, we record the entity for each asset and stock location. Shared assets go on a separate list for your decision.
Do you set the fair value of the assets?+
No. This service gives quantities, locations, tag numbers and condition notes. Your valuation team sets the fair values. CPCON also has a separate valuation advisory practice, if you want one team for both tasks.
Can our auditor observe the count?+
Yes. We send the count plan and the schedule before the count. Your auditor can observe the count and do test counts. The auditor decides what evidence is sufficient for the audit.
Get an opening balance sheet count proposal
Tell us the sites, the asset types and the acquisition date. We reply with the scope, the crew plan and a written quote.
This page gives general information. It is not legal, accounting or audit advice. Your auditor and advisors make the accounting decisions.