
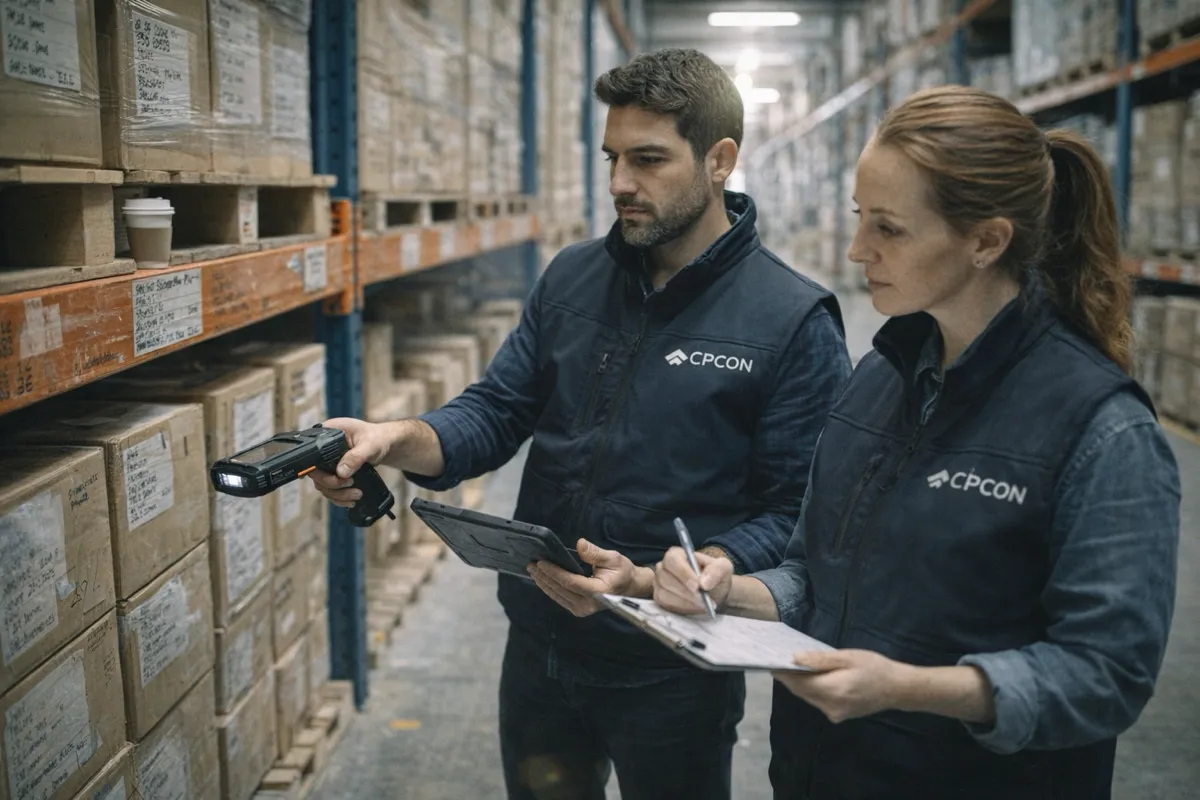
A year-end physical inventory count sets the stock quantity on your balance sheet. Auditors, lenders and tax filers all use that number. A plan made early lowers the risk of a late or disputed count.
This guide is for plant, warehouse and healthcare supply teams. It shows what to decide, what to settle before count day and what auditors expect. It also shows when an outside team helps.
Why the year-end count matters
Your inventory records say what you should hold. The count shows what you do hold. The two numbers must agree before you close the year. Three groups use the result:
- Finance. The count supports the inventory value in your financial statements. Read our guide to ASC 330 inventory accounting.
- Auditors. An auditor uses the count as evidence that the stock exists.
- Tax. Federal income tax rules need inventories at the start and end of each taxable year when merchandise is an income-producing factor.[S1] Some small taxpayers have an exemption. Ask your tax adviser.
Decide the count type
Choose the count type before you choose a date. You have two main options.
When a wall-to-wall count fits
A wall-to-wall count covers all stock, in all areas, on one date. It fits when one or more of these points are true:
- Your records are weak or old.
- Your system changed during the year.
- Your auditor wants one count date.
- The site can stop work for a planned period.
For the full service, see our wall-to-wall inventory audits.
When a cycle program fits
A cycle count program counts part of the stock on a rotating schedule through the year. It fits when your records are strong and the site must keep running. Your auditor must accept the program.
PCAOB AS 2510 gives the rule for auditors. It says that some companies use controls and methods that are "highly effective in determining inventory quantities".[S2] It adds that such methods can be "sufficiently reliable to make unnecessary an annual physical count of each item of inventory".[S2] The auditor must still be satisfied with the method. Read how auditors view statistical sampling of inventory counts. For more on the trade-offs, see our cycle count inventory guide and our cycle count program.
What to settle before count day
Decide these three items early. Write each one down.
Cut-off rules
Cut-off is the point in time that divides this count from the next one. A receipt, shipment or transfer must fall on one side of the line only. Write one cut-off rule for receipts, shipments, transfers, returns and production. Name the person who signs it.
Scope
List each stock type that the count covers:
- Raw material
- Work in process
- Finished goods
- Maintenance, repair and operations (MRO) parts and spares
- Stock held for other owners (consigned stock)
- Stock held at outside sites or warehouses
- Damaged, obsolete or held stock
Some stock sits with an outside custodian. AS 2510 says the auditor "ordinarily would obtain direct confirmation in writing from the custodian".[S2] Add those sites to your list.
Who counts
You have three choices:
- Your own team. Your people know the stock. They also run the site, so they have less time.
- An outside team. It adds trained people for a short period. Your staff keep their normal work.
- A hybrid. Your team counts some areas. An outside team counts the rest.
What auditors expect to see
Tell your auditor your count date early. Ask what the auditor will observe. AS 2510 is the PCAOB standard for auditing inventories in audits of public companies. For other audits, ask your auditor which standard applies.
The standard sets this expectation for one case. The quantities come only from a physical count. All counts happen on one date near the balance-sheet date. Then "it is ordinarily necessary for the independent auditor to be present at the time of count".[S2] The auditor then checks the methods of inventory-taking by observation, tests and inquiries.
Your team can prepare for this. Keep your count plan, your cut-off rule and your count records in one place. If your auditor needs an observer, learn about our inventory observation support.
Year-end checklist
Use these 10 items as a start. Each item says what to do. Your own policies set how.
- Pick the count date and tell your auditor.
- Pick the count type: wall-to-wall or cycle program.
- Write the cut-off rule.
- Name one owner for the whole count and one owner for each area.
- List all sites, including outside sites.
- List the stock types in scope and the stock types out of scope.
- Clean item numbers, units of measure and locations in your system.
- List stock that is damaged, obsolete, on hold or owned by others.
- Confirm the count team and the training it needs.
- Agree who reviews each difference and who approves each adjustment.
Typical problems after the count
Most year-end problems appear after the count, not during it. Plan an owner for each one.
| Problem | Risk | Owner |
|---|---|---|
| Unreconciled differences | The books do not match the floor. The close is late. | Finance lead |
| Missing or weak cut-off | Stock is counted twice or not at all. | Logistics lead and finance lead |
| Late count sheets or data | The review starts late. Auditors wait. | Count lead |
When to hire a count team
Think about an outside team when one or more of these points are true:
- You have many sites and one count date.
- Your staff cannot leave daily work.
- You need a result for an auditor, a lender or a buyer.
- Your last count had large differences.
- You changed systems or bought a company.
Our project managers, with our engineering and production department, plan your count. CPCON reports 500+ Projects Completed. Tell us your sites, your count date and your scope. We then write a scope for you. See our physical inventory counting services.
Frequently asked questions
- Do we need a full count every year?
- Not always. It depends on your records, your policies and your auditor. AS 2510 allows other methods when they are reliable and the auditor accepts them.[S2] Ask your auditor before you decide.
- Who may count?
- Your own trained staff, an outside team or both. Your policies and your auditor set the limits. Plan who counts which area before count day.
- What is cut-off?
- Cut-off is the point in time that divides this count from the next one. It decides which year owns each receipt, shipment and transfer.
- Can a cycle count replace the year-end count?
- Sometimes. Your records must be strong, and your auditor must accept the program. Some sites run a cycle program and a smaller year-end true-up. Our physical inventory counting services cover both models.
Plan your year-end count
Send us your site list and your count date. We write a scope for you. Start with our physical inventory counting services. You can also watch our year-end counts webinar.
Sources
- [S1] US Government Publishing Office, eCFR, 26 CFR 1.471-1 "Need for inventories": https://www.ecfr.gov/current/title-26/section-1.471-1 (read 2026-11-11).
- [S2] PCAOB, AS 2510 "Auditing Inventories", paragraphs .09, .11 and .14: https://pcaobus.org/oversight/standards/auditing-standards/details/AS2510 (read 2026-11-11).